
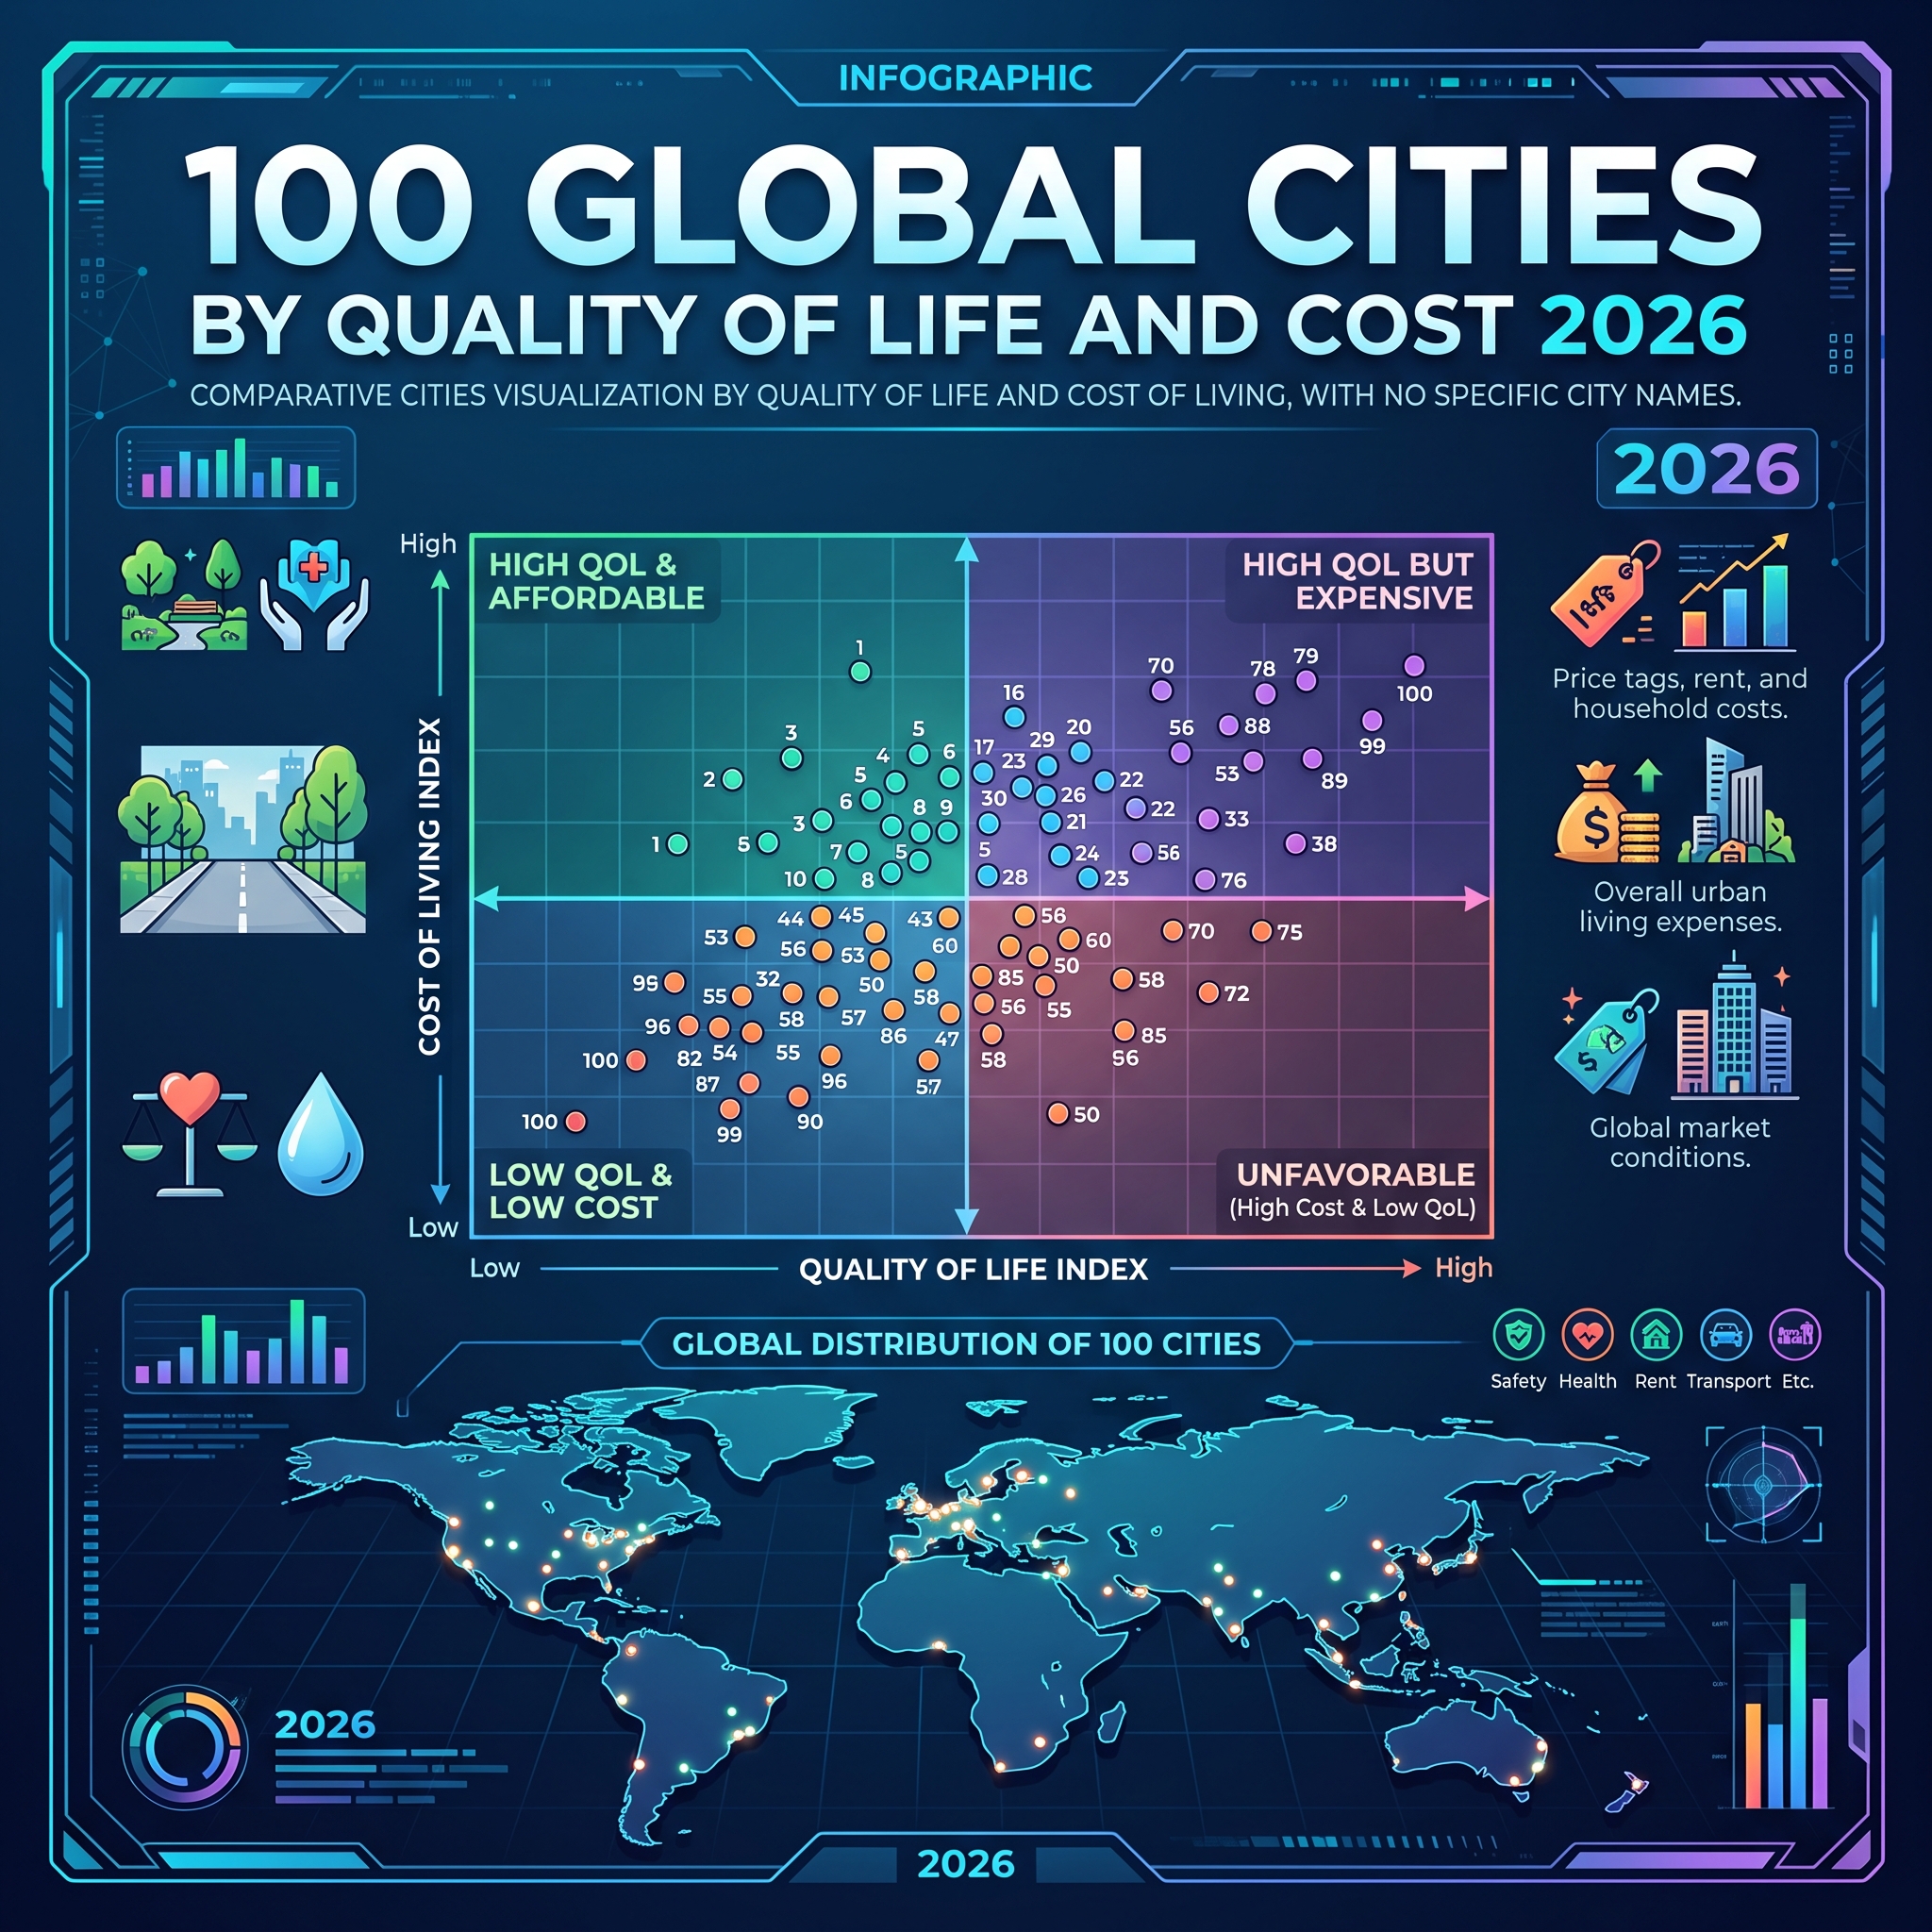
London, Paris, and New York sit in the bottom 25% of city value rankings when comparing operational cost against everyday quality of life. High living expenses, aggressive taxes, and low perceived livability define these legacy capitals. Yet retail executives and mid-market consumer packaged goods (CPG/FMCG) brands continue to burn millions of euros opening flagship stores in these exact locations.
Opening a trophy store on Oxford Street, the Champs-Élysées, or 5th Avenue looks impressive in an investor slide deck. On the balance sheet, however, these locations frequently turn into black holes for capital.

Infographic: Visual capitalist / Valerii Emelianov
The K-Shaped Market: Why Mid-Tier Retail Fails in Tier-1 Capitals
Addressing Tier-1 retail challenges, global capitals no longer have a unified consumer base. The local economy has split into a sharp K-shaped curve.
| Top 10% Wealthy & Global Tourists | ➔ | Pure Luxury / High Margin |
| ↓ THE SQUEEZED MIDDLE (Mid-Market Brands Die Here) ↓ | ||
| 90% Local Working & Middle Class | ➔ | Hard Discount / Private Label |
The Luxury Ceiling and the Hard Discount Floor
At the top arm of the K-curve, international tourists, ultra-high-net-worth individuals, and corporate executives continue to spend on high-end luxury goods, boutique services, and premium dining. Luxury fashion houses and prestige brands thrive because their gross margins (often 70% to 85%) can absorb absurdly high commercial rents.
At the bottom arm of the K-curve, the local middle class faces severe pressure from housing costs, utility bills, and transport expenses. To protect their household budgets, they trade down immediately. They abandon mid-priced brand names and buy basic staples at hard discounters like Lidl, Aldi, Mercadona, and Action, or rely entirely on supermarket private labels.
The Collapse of the Middle-Market Consumer Base
This polarization destroys the middle tier, a key characteristic of the K-shaped market retail environment. Mid-market brands offer good quality at an accessible price point, but “accessible” is no longer cheap enough for the squeezed local population, while the product lacks the prestige required by luxury shoppers. When your core demographic disappears from central urban areas, maintaining a large physical footprint becomes impossible.
Retail Unit Economics: Footfall Traps, Commercial Leases, and Margin Decay
High pedestrian traffic is the most deceptive metric in commercial real estate. Landlords sell footfall counts, but footfall does not equal revenue.
The High Footfall Mirage vs. Low Basket Conversion
A flagship store in central London or Paris may see 40,000 people walk past its doors daily. But who are these people?
- Commuters in a rush to reach a train platform.
- Budget tourists who step inside to use the air conditioning or browse.
- Window shoppers buying a single €3 beverage or small impulse snack.
Selling low-ticket items with a tiny gross margin cannot sustain a high-cost real estate strategy. If a store sells 1,500 low-value units a day, the cash generated rarely covers the daily operational baseline.
Fixed OpEx Breakdown: Prime Lease Rates and Labor Inflation
In prime central shopping corridors across Western Europe and the United States, commercial lease rates easily exceed €2,500 to €3,500 per square meter per year.
| Cost Component | Tier-1 Capital (London / Paris / NYC) | Secondary Hub (Valencia / Porto / Malaga) |
|---|---|---|
| Prime Retail Lease | €2,500 – €3,500+ / m² / year | €400 – €900 / m² / year |
| Fit-out CapEx | €2,000 – €4,000 / m² | €800 – €1,500 / m² |
| Store Staff Turnover | High (35% – 60% annually) | Moderate to Low (10% – 25%) |
| Typical Payback Period | 5 – 8 years (or never) | 18 – 30 months |
| Breakeven Daily Basket | High volume of high-margin items | Manageable volume of standard baskets |
Beyond lease costs, operational expenditures (OpEx) continue to rise:
- Wages and Social Taxes: High cost of living forces continuous wage increases just to keep basic retail positions filled.
- Staff Turnover: Retail employees in Tier-1 cities move frequently due to long commutes and unaffordable urban housing, raising recruitment and training costs.
- Logistics and Deliveries: Urban access restrictions, low-emission zones, and congested freight routes add significant distribution surcharges to daily restocking.
The Secondary City Advantage: Why Valencia, Porto, and Malaga Offer Better ROI
While capital cities struggle with cost disease, secondary European and regional hubs are experiencing sustained economic inflow.
& Sustainable Operating Margin
Lifestyle Migration and Distributed Purchasing Power
Cities like Valencia, Porto, Malaga, Alicante, and Tallinn are no longer seasonal tourist towns. Over the past five years, remote work, cross-border corporate relocations, and digital infrastructure improvements shifted tens of thousands of skilled professionals and stable families into these markets.
These residents bring strong disposable incomes but benefit from lower living costs. Unlike the stressed middle class in London or Paris, consumers in secondary hubs have real discretionary income left over at the end of the month for dining, lifestyle retail, and quality consumer goods.
Lower Store CapEx and Accelerated Capital Payback
Setting up a store in a secondary hub changes the financial equation:
- Lower Rent-to-Revenue Ratio: Prime commercial rents are 60% to 75% cheaper than in Tier-1 capitals, keeping occupancy costs below 10-12% of gross revenue.
- Cheaper Fit-Out CapEx: Contractor rates, municipal permitting fees, and initial build-out costs are dramatically lower.
- Sustained Year-Round Demand: An active local population combined with seasonal tourism provides steady, year-round baseline sales rather than erratic spikes.
Strategic Playbook: 4 Rules for Profitable Retail Store Network Expansion
To build a resilient and profitable store network, retail and consumer brands must shift their retail store profitability strategy from prestige-driven expansion to cash-flow-driven distribution.
- Eliminate Mid-Market Concepts in Mega-CapitalsDo not launch standard mid-priced retail stores in high-rent capital centers. In ultra-expensive cities, only two models work: hard discount (high volume, bare-bones OpEx) or true luxury (extreme margins, high average basket value). The middle space is structurally unprofitable.
- Follow Regional Lifestyle and Talent CorridorsDirect expansion capital into fast-growing secondary markets. Look for cities with net positive migration, expanding international flight connections, modern co-working infrastructure, and affordable housing.
- Measure Contribution Margin per Square Meter, Not Gross RevenueA store generating €3,000,000 in gross annual revenue with a €2,900,000 cost structure is a dangerous liability. A secondary store generating €900,000 in revenue with €550,000 in total costs delivers €350,000 in clean EBITDA. Focus on the bottom line.
- Build Regional Store Density Over Isolated FlagshipsInstead of spending €5 million on a single central London store, deploy that capital to build a cluster of 5 to 7 optimized locations across Valencia, Malaga, and Porto. Clustering lowers regional marketing costs, streamlines logistics routes, and reduces overall supply chain risk.
Frequently Asked Questions (FAQ)
What is the primary difference between Tier-1 and secondary city retail economics?
Tier-1 cities feature high commercial rents (€2,500+/m²), high labor costs, and extreme market polarization. Secondary cities offer lower occupancy costs (€400–€900/m²), lower initial capital expenditures, and higher disposable income retention among residents, leading to faster store payback periods.
Why does high pedestrian footfall fail to generate profit for mid-market brands?
High footfall often consists of commuters or low-intent tourists. If these visitors only buy low-ticket, impulse products (like drinks or snacks), the low average order value (AOV) and narrow gross margins cannot cover the high fixed rent and operational expenses of prime real estate.
What is a healthy rent-to-revenue ratio for a retail store?
For most FMCG, specialty food, and lifestyle retail brands, total occupancy cost (base rent + service charges) should ideally remain between 8% and 12% of gross sales. In central London or Paris, this ratio frequently climbs past 20% to 25%, making baseline profitability nearly impossible.
Which secondary European cities currently offer strong retail investment potential?
Cities like Valencia, Malaga, Porto, Krakow, and Tallinn provide strong infrastructure, growing populations of remote and corporate professionals, manageable commercial lease rates, and steady year-round local consumer demand.
Related posts:
 Car Color Market Share Trends 2025: Grayscale Hits 80.4%
 Inditex Financial Results 1H 2026: Sales €19.8B vs Opex Hit
 GLP-1 Retail Market Trends 2026: Data, Forecasts & Consumer Shifts
 Seasonal Retail Inventory Management: 85/15 Buffer Model
 Aldi vs Tesco Sainsbury Loyalty Schemes: 2026 Analysis
 Emerging Megacities: FMCG Retail Trends and Consumer Shifts by 2050
Leave a Reply